Leduc runs on early starts. Shifts at the airport, rotations out of Nisku, a commute up the QE2 to Edmonton: a lot of people here depend on a vehicle and a steady paycheque, and when one of them hiccups, money gets tight fast. A blown tire on the highway or a short cheque after a slow rotation can leave you a few hundred dollars short before payday.
If you’re weighing Leduc payday loans, this guide walks through how they work under Alberta’s rules, what they cost, how the repayments fit around your pay schedule, and what’s worth trying first. Alberta’s rules are different from the rest of Canada, so even if you’ve borrowed somewhere else, a few things here will be new.
Who’s writing this: CCFD is a free referral and financial-information service, not a lender. If you apply through CCFD, your application goes to a lender licensed in Alberta, and that lender decides whether to approve you and sets the terms.
The short answer
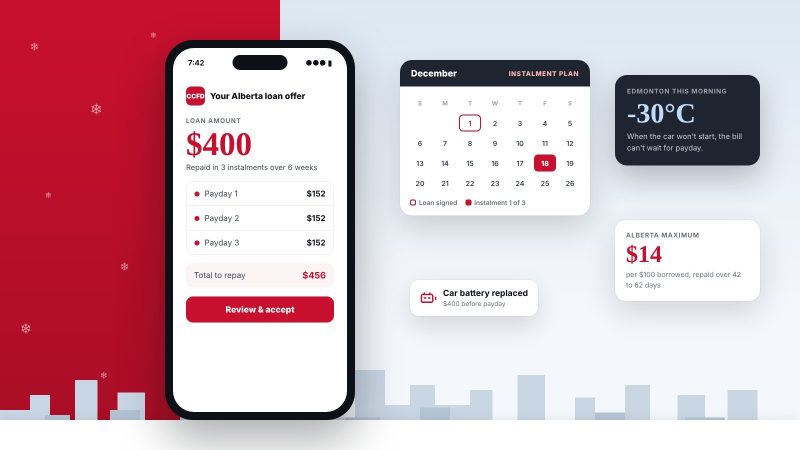
Payday loans are available to Leduc residents from lenders licensed by the Government of Alberta, online or in person. You can borrow $100 to $1,500, and the cost can’t exceed $14 for every $100 borrowed. Here’s the part that surprises people: in Alberta you don’t repay the whole thing on your next payday. The law requires at least two instalments spread over 42 to 62 days, matched to your pay dates. You have two business days to cancel after signing.
What it costs
The $14 cap includes every fee, and it’s the same whether you repay in six weeks or eight:
| You borrow | Maximum cost | Maximum you repay |
|---|---|---|
| $300 | $42 | $342 |
| $600 | $84 | $684 |
| $1,000 | $140 | $1,140 |
| $1,500 | $210 | $1,710 |
Spread over six weeks, $14 per $100 is a lower annual rate than a classic two-week payday loan, but it’s still far more expensive than an overdraft, a credit card or a credit union loan. The dollar cost is what matters: borrowing $600 costs up to $84, and borrowing $300 instead costs $42. Only borrow what the problem actually needs.
How the instalments line up with your pay
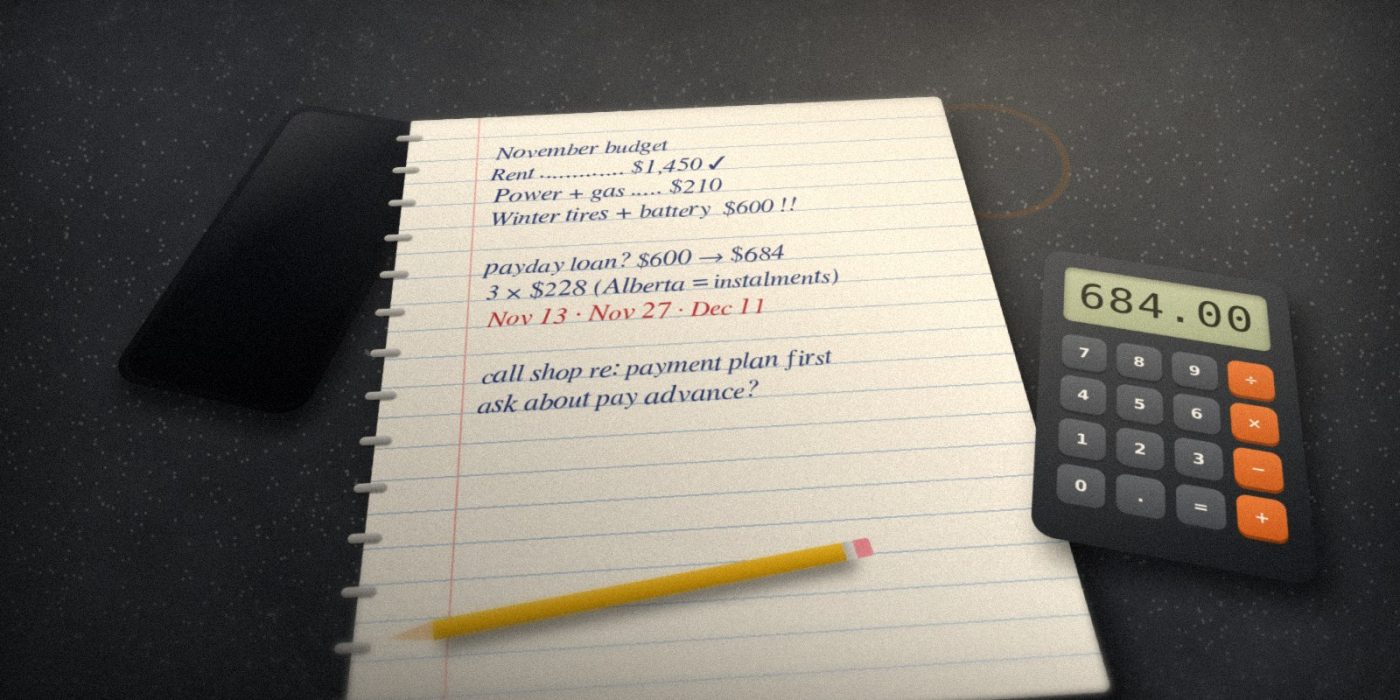
Say you sign a $600 loan on a Friday, October 30, and you’re paid every second Friday. Your total is $684, and an Alberta lender might spread it like this:
| Payday | Instalment | Left to repay |
|---|---|---|
| Friday, November 13 | $228 | $456 |
| Friday, November 27 | $228 | $228 |
| Friday, December 11 | $228 | $0 |
Because the loan stays on your budget for six weeks, check each of those paydays, not just the first one. If you work rotations, make sure the dates line up with when your pay actually lands, and not with a shift that might get cut. You can repay early at any time without a penalty.
Who can apply in Leduc?
Each lender sets its own criteria, and approval is never guaranteed. Most licensed Alberta lenders look for:
- An Alberta address, and being 18 or older.
- Regular income. Employment income is the most common. Some lenders also consider self-employment, EI, CPP or disability benefits when the deposits are regular.
- An active Canadian chequing account in your name that can receive deposits and pre-authorized payments.
- A working phone number and email address.
Bad credit is often considered. Many lenders put more weight on your income and recent bank activity than on your credit score, and some use only a soft check. Others do review your credit file, so a low score isn’t automatically a no, but no one can promise a yes.
How to apply online
- Work out the exact amount you need and which paydays will cover the instalments.
- Fill in the online application. It takes about five minutes: contact details, employer and pay dates, and your banking information.
- Verify your income. Most lenders use a secure, read-only bank connection; some ask for a pay stub.
- Read the offer. Check the Alberta licence number, the total cost in dollars and every instalment date.
- Accept only if it fits. You’re never obliged to take an offer, and you can still cancel within two business days.
- Get your money. After you sign, lenders usually send funds by Interac e-Transfer, often the same day. Timing depends on the lender’s review and your bank.
When it makes sense, and when it doesn’t
A payday loan can be a reasonable bridge for a one-time cost you can’t put off and can clearly repay: a tire or a battery you need to get to an early shift, a utility disconnection notice, or an urgent dental bill.
It’s the wrong tool for a gap that comes back every month, like rent that’s always short, or for a slow stretch between rotations when you don’t know when the next full cheque is coming. In those cases, the instalments will overlap with the next shortfall, and Alberta doesn’t let a lender roll one loan into another to cover it.
Cheaper help in and around Leduc
- Call the company you owe. Utility retailers, phone companies, landlords and many repair shops will split a bill or move a due date if you ask before it’s late.
- Leduc FCSS: the City of Leduc’s Family and Community Support Services can point you to local programs and supports.
- Leduc & District Food Bank: if groceries are part of the squeeze, a food bank visit can free up cash for the bill that can’t wait.
- Money Mentors: an Alberta non-profit offering free credit counselling and repayment plans.
- 211 Alberta: dial 2-1-1 for emergency help with rent, utilities and food.
- Your employer or credit union: ask about a pay advance on hours you’ve already worked, or a small loan or overdraft.
Before you accept any offer
- Total repayment: the full amount that will leave your account, not just what you borrow.
- Every instalment date lines up with a payday you can count on.
- The Alberta licence number is on the agreement. Online lenders need the same licence as a storefront.
- Late terms: what happens if a payment can’t be processed, in writing.
- No upfront fees: a licensed lender never asks you to pay, send an e-Transfer or buy gift cards before you get the loan.
For every rule in detail, read our Alberta payday loans guide. If you work or shop in the city, our Edmonton payday loans page covers nearby help, and you can compare payday-loan rules by province.
Frequently asked questions
Can I get a payday loan in Leduc with bad credit?
Often, yes. Many lenders focus on income and recent bank activity rather than your credit score, and some use only a soft check. Others do review your credit file, and approval is never guaranteed.
How quickly can I receive funds?
The application takes about five minutes and decisions are often quick once your income is verified. After you sign, lenders usually send funds by Interac e-Transfer, often the same day, though your bank’s processing can add time.
Do I repay a Leduc payday loan on my next payday?
No. In Alberta, payday loans are repaid in at least two instalments over 42 to 62 days, lined up with your pay dates.
How much can I borrow in Alberta?
Between $100 and $1,500. Lenders look at your income and often approve less on a first loan.
Is CCFD a direct lender?
No. CCFD is a free referral and financial-information service. It sends your application to a lender licensed in Alberta, and that lender provides the loan and sets the terms.
Is applying free?
Yes. Applying through CCFD is free, and you can review the lender’s offer before deciding whether to accept it.
This article is general information, not financial advice. Reviewed against Government of Alberta and Financial Consumer Agency of Canada rules in November 2026. Payday loans are high-cost credit for short-term emergencies.