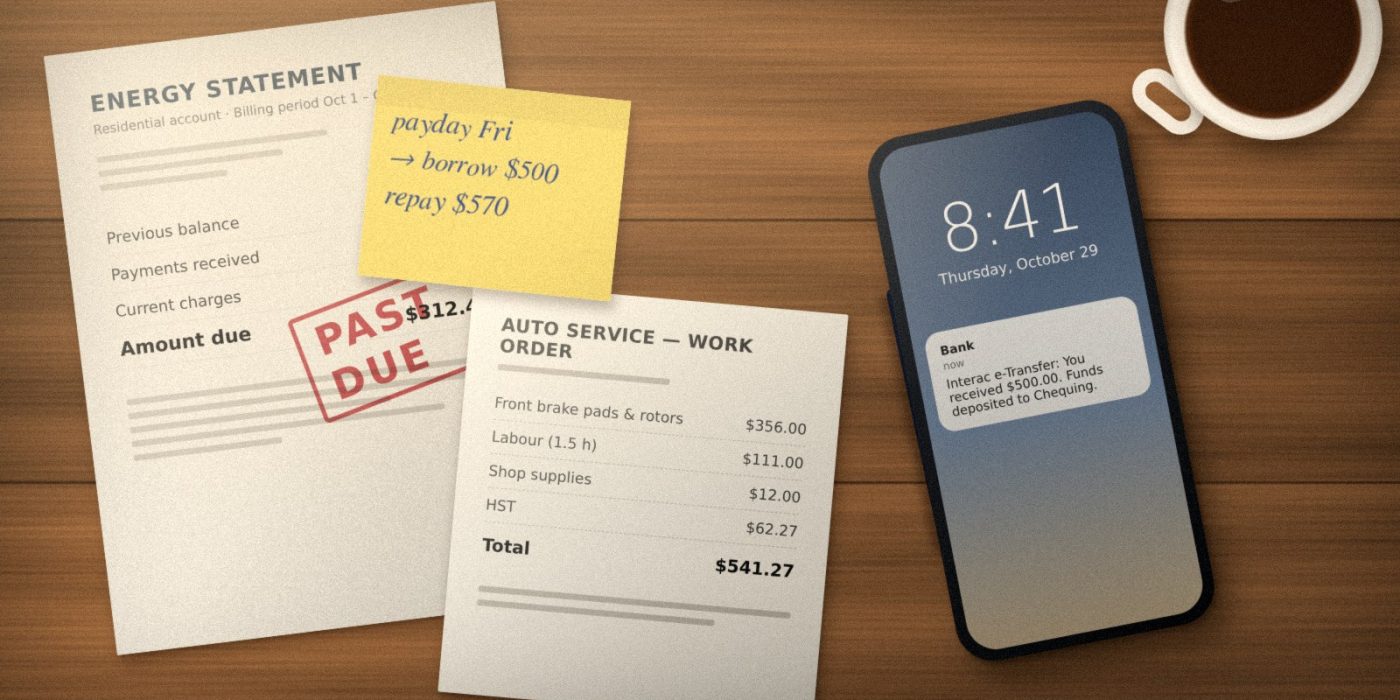
Toronto is an expensive city to be short in. When rent takes most of a paycheque, it only takes one surprise, like a transmission repair, a dental bill or a paycheque that lands two days late, to leave you scrambling for a few hundred dollars before payday. Online payday loans are built for that moment, and they’re advertised everywhere from TTC ads to your phone.
This guide explains how Toronto payday loans work under Ontario’s rules: what they cost in real dollars, how much you can borrow on your income, what happens if you need a second or third loan, and the cheaper options Toronto residents should check first.
Who’s writing this: CCFD is a free referral and financial-information service, not a lender. If you apply through CCFD, your application goes to a lender licensed in Ontario, and that lender decides whether to approve you and sets the terms.
The short answer
A payday loan in Toronto is a loan of up to $1,500, usually repaid in one payment on your next payday, from a lender licensed by the Government of Ontario. It can cost no more than $14 for every $100 you borrow, and a single loan can’t be more than 50% of your net pay. You have two business days to cancel after signing, and approved funds are usually sent by Interac e-Transfer.
What a payday loan costs in Ontario
The $14 limit includes every fee. A lender can charge less, but never more. Here’s the most you would repay:
| You borrow | Maximum cost | Maximum you repay |
|---|---|---|
| $300 | $42 | $342 |
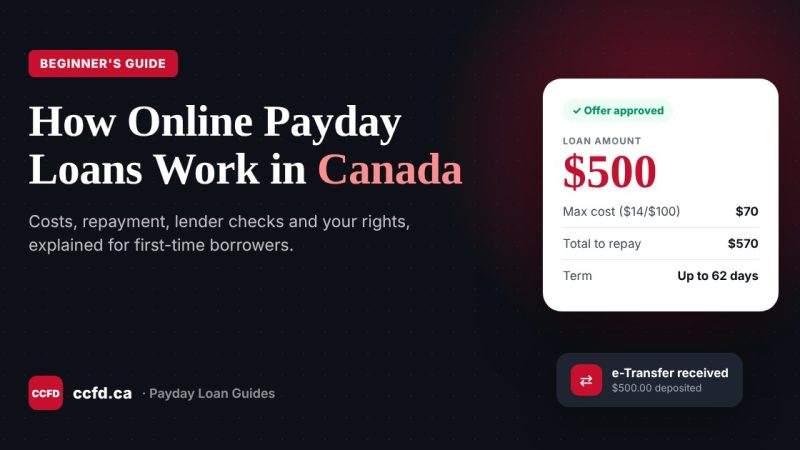
| $500 | $70 | $570 |
| $1,000 | $140 | $1,140 |
| $1,500 | $210 | $1,710 |
On a two-week loan, $14 per $100 works out to an annual rate of roughly 365%. For comparison, a credit card cash advance on the same $500 for two weeks usually costs well under $10 in interest, plus any advance fee. That’s why a payday loan only makes sense when cheaper options really aren’t available in time.
If a payment fails, Ontario allows one returned-payment fee (capped at $20) and interest of up to 2.5% a month on the overdue amount. Those charges are small compared with the loan fee, but they add up if a missed payment drags on, so call the lender before the due date if you know you’ll be short.
How much can you borrow on your income?
Ontario’s 50% rule is the limit most Toronto borrowers bump into. It’s based on your net pay, what actually lands in your account, for the period of the loan. A few examples for a two-week loan:
| Take-home pay every two weeks | Most a lender can offer | Maximum cost |
|---|---|---|
| $1,000 | $500 | $70 |
| $1,600 | $800 | $112 |
| $2,400 | $1,200 | $168 |
| $3,000 or more | $1,500 | $210 |
If the expense is bigger than half your paycheque, a payday loan won’t cover it, and that’s by design. A larger repair or a security deposit is better handled with a payment plan, a credit union loan or one of the programs below.
Do you qualify?
Each lender sets its own criteria, and approval is never guaranteed. Most licensed Ontario lenders look for:
- An Ontario address and being 18 or older.
- Regular income for at least a few months. Employment income is most common; some lenders also consider self-employment, EI, CPP or disability benefits when the deposits are regular.
- An active Canadian chequing account in your name that can receive deposits and pre-authorized payments.
- A working phone number and email address.
Bad credit is often considered. Many lenders focus on your income and recent bank activity, and some use only a soft credit check that doesn’t affect your score, while others do review your credit file. A low score isn’t automatically a no, but nobody can promise approval. Our guide to bad credit payday loans explains how lenders check.
How to apply online from Toronto
- Decide on the smallest amount that solves the problem. Every $100 costs up to $14.
- Fill in the online application. It takes about five minutes: contact details, employer and pay dates, and your banking information.
- Verify your income. Most lenders use a secure, read-only bank connection; some ask for a pay stub.
- Read the offer. Look for the Ontario licence number, the total repayment in dollars and the due date. Make sure the due date falls after your next deposit.
- Accept only if it fits. You’re never obliged to take an offer, and you can still cancel within two business days of signing.
- Get your money. After you sign, lenders usually send funds by Interac e-Transfer, often the same day. Timing depends on the lender’s review and your bank.
Second and third loans: Ontario’s extended payment plan
Ontario has a rule most borrowers don’t know about. You can’t get a new payday loan from the same lender until the current one is paid in full, and if you take three payday loans within 63 days, the lender has to offer an extended payment plan on the third one.
If you’re paid weekly, every two weeks or twice a month, that plan spreads the third loan over at least three paydays, with no single payment above 35% of the total. If you’re paid monthly, it’s spread over at least two. There’s no extra charge for the plan, and you can pay it off early.
If you’ve reached that third loan, it’s also a good moment to pause. Borrowing again to cover the gap left by the last loan is the pattern that turns a $500 emergency into months of fees. A free conversation with a credit counsellor can help you find a way out.
Cheaper options to check first in Toronto
Before you apply, it’s worth a few phone calls. Several of these cost nothing:
- Toronto Rent Bank: help for Toronto tenants who are behind on rent or need help with a deposit.
- LEAP and OESP: Ontario’s Low-income Energy Assistance Program can help with overdue hydro or gas bills, and the Ontario Electricity Support Program lowers monthly electricity costs.
- TTC Fair Pass: discounted fares for eligible low-income residents, useful if a car repair has to wait.
- A payment arrangement: phone companies, utilities and many landlords will split a bill or move a due date if you call before it’s late.
- Credit Canada: a non-profit offering free credit counselling and debt management plans.
- 211 Ontario: dial 2-1-1 for food, housing and emergency financial help across Toronto.
Before you accept any offer
- Total repayment: the full amount that will leave your account, not just the loan.
- Due date: after your next pay deposit, with enough left for rent and groceries.
- Licence: an Ontario payday lender licence number on the agreement. You can check it with Consumer Protection Ontario.
- Late terms: the returned-payment fee and default interest, in writing.
- No upfront fees: a licensed lender never asks you to pay, send an e-Transfer or buy gift cards before you get the loan.
For every Ontario rule in detail, see our Ontario payday loans guide. For local help and Toronto-specific questions, visit our Toronto payday loans page.
Frequently asked questions
Can I get a payday loan in Toronto with bad credit?
Often, yes. Many lenders focus on income and recent bank activity rather than your credit score, and some use only a soft check. Others do review your credit file, and approval is never guaranteed.
How quickly can I get the money?
The application takes about five minutes and many decisions are quick once your income is verified. After you sign, lenders usually send funds by Interac e-Transfer, often the same day, though your bank’s processing can add time.
How much can I borrow with a payday loan in Ontario?
Up to $1,500, and no more than 50% of your net pay for the loan period. Lenders often approve less on a first loan.
Who licenses payday lenders in Ontario?
The Government of Ontario licenses payday lenders and brokers under the Payday Loans Act, 2008. The licence number must appear on your agreement, and you can verify it with Consumer Protection Ontario.
Is CCFD a direct lender?
No. CCFD is a free referral and financial-information service. It sends your application to a lender licensed in Ontario, and that lender provides the loan and sets the terms.
Is applying free?
Yes. Applying through CCFD is free, and you can review the lender’s offer before deciding whether to accept it.
This article is general information, not financial advice. Reviewed against Government of Ontario and Financial Consumer Agency of Canada rules in October 2026. Payday loans are high-cost credit for short-term emergencies.