It always seems to happen in the week before payday. The car won’t turn over on a -30°C morning, the furnace starts making a noise you can’t ignore, or the phone bill comes in higher than you planned. If you live in Edmonton and need money before your next paycheque, an online payday loan is one of the options you’ll see advertised everywhere.
This guide explains how Edmonton payday loans actually work under Alberta’s rules, what they cost in real dollars, how the repayments line up with your pay schedule, and what’s worth trying first. Alberta’s rules are different from most other provinces, so even if you’ve borrowed elsewhere in Canada, some of this will be new.
Who’s writing this: CCFD is a free referral and financial-information service, not a lender. If you apply through CCFD, your application goes to a lender licensed in Alberta, and that lender decides whether to approve you and sets the terms.
The short answer: how payday loans work in Edmonton
An Edmonton payday loan is a small loan of $100 to $1,500 from a lender licensed by the Government of Alberta. It can cost no more than $14 for every $100 you borrow, including all fees. Unlike most provinces, Alberta doesn’t let you repay it in one lump sum on your next payday: you repay it in at least two instalments over 42 to 62 days, lined up with your pay dates. You can cancel within two business days of signing, and a lender can’t roll your loan into a new one.
What it costs in real dollars
The $14 limit applies whether you borrow from a storefront or from a lender online. Here’s the most a licensed lender can charge:
| You borrow | Maximum cost | Maximum you repay |
|---|---|---|
| $300 | $42 | $342 |
| $500 | $70 | $570 |
| $1,000 | $140 | $1,140 |
| $1,500 | $210 | $1,710 |
Fourteen dollars sounds modest, but it’s charged for weeks, not a year. On a two-week loan, $14 per $100 works out to an annual rate of about 365%. Because Alberta loans run at least 42 days, the annual rate on your agreement will be lower than that, but the dollar cost is the same. The cheapest payday loan is always the smallest one that solves the problem.
How Alberta’s instalments fit your pay schedule
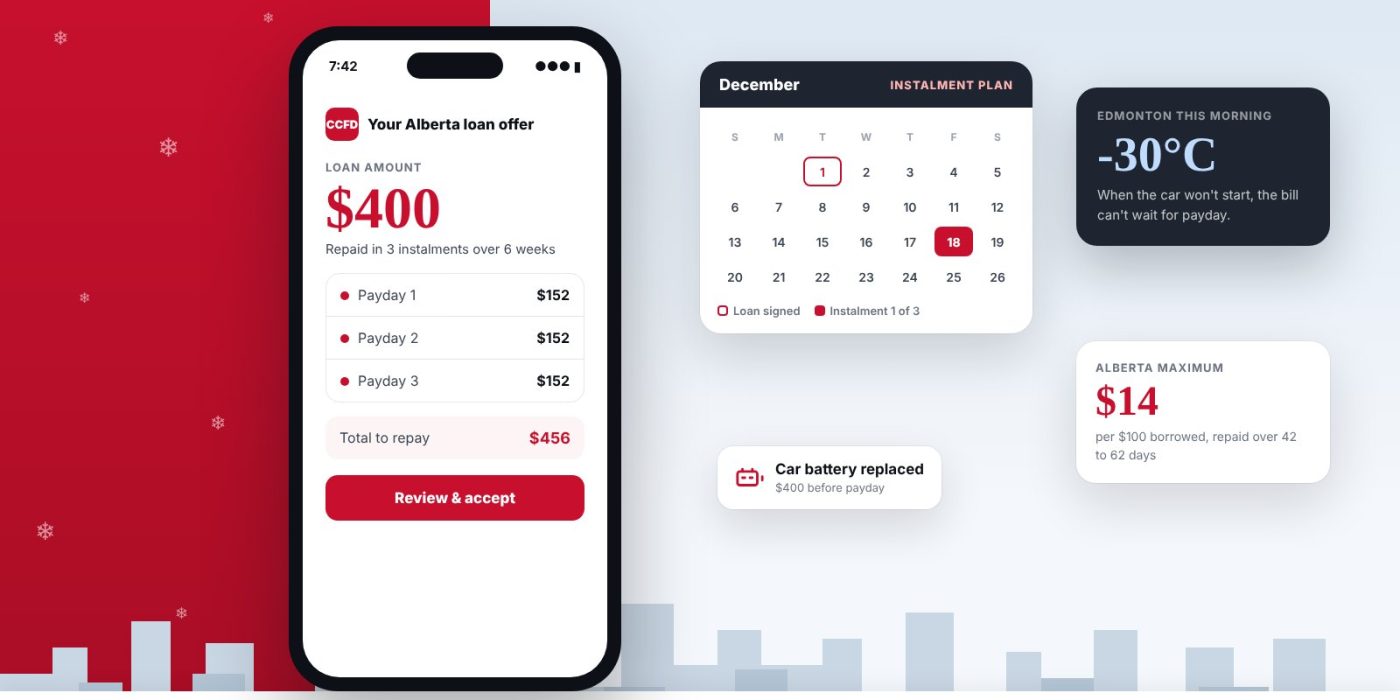
This is the part most Edmontonians don’t expect. Your loan agreement spreads the total across your paydays, and the schedule has to be in writing before you sign. Here’s what borrowing $400 (total to repay: $456) could look like on three common pay schedules:
| How you’re paid | Typical schedule | Each payment |
|---|---|---|
| Every two weeks | 3 paydays over 6 weeks | $152 |
| Twice a month (15th and last day) | 3 paydays over about 6 weeks | $152 |
| Monthly | 2 paydays over about 8 weeks | $228 |
Smaller payments are easier to absorb, which is the point of the rule. The trap is that the loan stays on your budget for six weeks or more. Before you sign, write each payment date into your calendar next to rent and your other bills, and make sure every one of those paydays can carry it.
Do you qualify? What lenders look for
Each lender sets its own criteria, and approval is never guaranteed. Most licensed Alberta lenders ask for the same basics:
- You’re 18 or older and live in Alberta.
- You have regular income. Employment income is the most common; some lenders also consider self-employment, EI, CPP or disability benefits if the deposits are regular.
- You have an active Canadian chequing account in your name that can receive deposits and pre-authorized payments.
- You have a working phone number and email address for your agreement and any verification.
You don’t need to be a Canadian citizen to apply, and there’s no single income threshold that applies to every lender. On credit: many payday lenders focus on your income and recent bank activity rather than your credit score, and some use only a soft check. Others do review your credit file. A low score doesn’t automatically rule you out, but no licensed lender can promise approval without checking anything. Our guide to how credit checks work explains the difference.
How to apply online from Edmonton
- Work out the exact amount you need. Not the most you can get. Every $100 costs up to $14.
- Fill in the online application. It takes about five minutes: contact details, employer and pay dates, and your banking information.
- Verify your income. Most lenders use a secure, read-only bank connection. Some ask for a pay stub instead.
- Read the offer carefully. Check the Alberta licence number, the total cost in dollars, and every instalment date against your paydays.
- Accept only if it fits. You’re never obliged to take an offer, and you can still cancel within two business days of signing.
- Get your funds. Once you sign, lenders usually send the money by Interac e-Transfer or direct deposit, often the same day. Timing depends on the lender and your bank.
Why Edmontonians end up short before payday
Most short-term borrowing in Edmonton comes down to timing, not overspending. The situations we hear about most often:
- Winter car trouble: a dead battery, a block heater, a tow after a cold snap.
- Heating and utility bills that jump in January and February.
- A new job with a long wait for the first paycheque, common in health care, government and the trades.
- Dental or prescription costs that aren’t fully covered.
- A rent payment that lands a few days before payday.
A payday loan can bridge a gap like these when it’s a one-time cost and you know which paycheques will repay it. It’s the wrong tool when the shortfall will be back next month, because the instalments will simply overlap with the next gap.
Try these first: cheaper help in Edmonton
A quick call can save you the borrowing cost entirely. Before you apply, check whether any of these fit your situation:
- Ask for a payment arrangement. Utility retailers, phone companies and many landlords will split a bill or move a due date if you call before it’s late.
- Ask about an employer pay advance on wages you’ve already earned, especially if you’re waiting on a first paycheque.
- Edmonton’s Ride Transit program offers a reduced-cost transit pass to eligible low-income residents, which can help if a car repair has to wait.
- Money Mentors, an Alberta non-profit, offers free credit counselling and can help if several bills are behind.
- 211 Alberta: dial 2-1-1 to find emergency food, rent and utility help in Edmonton.
- Your bank or credit union: an overdraft or small personal loan usually costs far less over the same few weeks.
Your rights as an Alberta borrower
- A licensed lender. Every payday lender serving Alberta, online or in a store, needs an Alberta payday loan licence. The number should be on your agreement.
- Full disclosure first. The amount, total cost, annual rate and every payment date must be in writing before you sign.
- Two business days to cancel, by returning the money, with no fee.
- No rollovers. A lender can’t give you a new payday loan to pay off an existing one.
- No upfront fees. Anyone asking for money, gift cards or crypto before you get a loan is running a scam.
- Early repayment is allowed without a penalty.
For every rule in detail, see our Alberta payday loans guide. For local examples and Edmonton-specific questions, our Edmonton payday loans page covers what’s different in the city, and you can compare the payday loan rules in other provinces.
Frequently asked questions
Can I get a payday loan in Edmonton with bad credit?
Often, yes. Many lenders focus on your income and bank activity rather than your credit score, so past credit problems don’t automatically disqualify you. Some lenders still review your credit file, and approval is never guaranteed.
How fast can I get money in Edmonton?
The application takes about five minutes, and decisions are often quick once your income is verified. After you sign, lenders usually send funds by Interac e-Transfer or direct deposit, often the same day, though your bank’s processing can add time.
Do I have to repay an Edmonton payday loan on my next payday?
No. In Alberta, payday loans are repaid in at least two instalments over 42 to 62 days, matched to your pay schedule.
How much can I borrow with a payday loan in Alberta?
Between $100 and $1,500. Lenders look at your income and often approve less on a first loan.
Is CCFD a lender?
No. CCFD is a free referral service. We send your application to a lender licensed in Alberta, and that lender approves the loan and sets its terms.
This article is general information, not financial advice. Reviewed against Government of Alberta and Financial Consumer Agency of Canada rules in October 2026. Payday loans are high-cost credit for short-term emergencies.