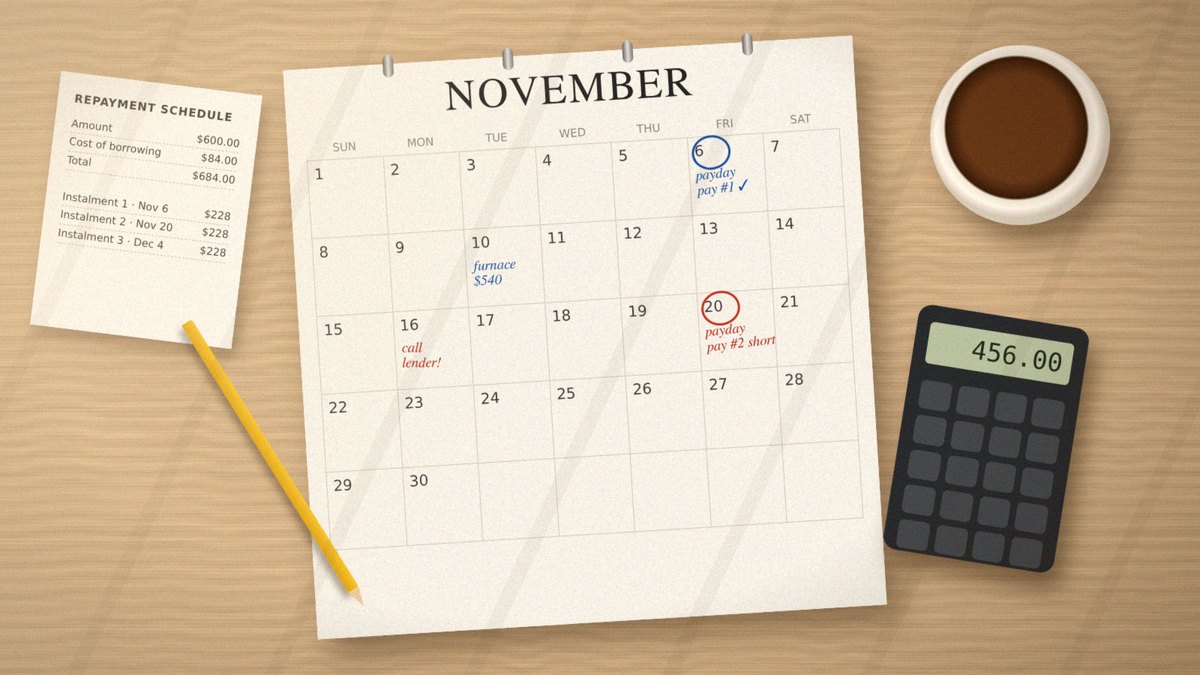
A missed payday loan payment rarely comes as a surprise. You usually see it coming a week out: a shift gets cancelled, the furnace quits, or a cheque from a client is late, and the instalment date on your agreement isn’t moving. The worst thing you can do at that point is nothing. The second worst is taking out another loan to cover the first one.
Alberta has some of the clearest payday loan rules in Canada, and they give borrowers more room than most people realize. This guide explains exactly what happens when an Alberta payday loan payment bounces, what it can cost, what lenders and collectors are not allowed to do, and the steps that usually keep a short-term problem from turning into a long one. It’s written for borrowers anywhere in the province, with notes for people in Edmonton.
First, Know What Kind of Loan You Have
Alberta doesn’t allow the classic “pay it all back on your next payday” loan. Every payday loan here has to be repayable in instalments over 42 to 62 days. If you’re paid every two weeks or more often, the payments have to be spread over at least three pay periods. That matters when you’re short, because missing one instalment is a very different problem from missing the whole balance.
Two more rules work in your favour. You can pay off all or part of the loan early at any time with no penalty, and a lender can’t give you a new payday loan while you still owe on the current one. The full set is in our guide to Alberta payday loan rules.
What Happens When an Instalment Bounces
Here’s the usual sequence when a pre-authorized debit fails because the money isn’t in your account. Timelines vary by lender, but the steps are fairly consistent.
- The payment is returned. Your bank may charge its own NSF fee, and the lender can charge a one-time fee for the dishonoured payment. It’s a one-time fee for each payment that bounces, and Alberta caps it by regulation.
- Default interest starts. On the overdue amount, the lender can charge interest of up to 2.5% a month. That’s on top of the original borrowing cost, which can’t exceed $14 for every $100 borrowed.
- The lender contacts you. Expect calls, texts or emails asking you to pay or set up an arrangement. Contact is limited to 7 a.m. to 10 p.m.
- The account may go to collections. If nothing is arranged, the lender can hand the debt to a licensed collection agency. A collection account can show up on your credit report and stay there for years.
- The lender may sue. For larger or long-ignored balances, a lender can take you to civil court. Only after it wins a judgment can it ask the court to garnish your wages or bank account.
Notice what isn’t on that list: police, jail, or anyone showing up to take your belongings. Debt collection in Alberta is a civil matter, and only a court-appointed civil enforcement agency can seize property, and only after a judgment.
A Worked Example: One Missed Instalment
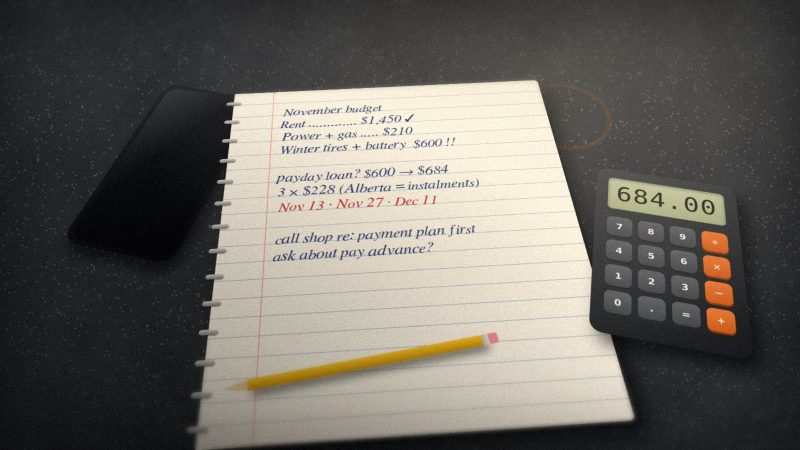
Say you borrowed $600 and you’re paid every two weeks. The borrowing cost at $14 per $100 is $84, so you owe $684 in three instalments of $228. You pay the first one, but the second one bounces.
| Amount | Notes | |
|---|---|---|
| Missed instalment | $228.00 | Still owed in full |
| Lender’s dishonoured payment fee | One-time fee | Capped by Alberta regulation |
| Your bank’s NSF fee | Varies by bank | Charged by your bank, not the lender |
| Default interest, first month | About $5.70 | 2.5% of $228 |
| Third instalment | $228.00 | Still due on its original date |
The fees on one missed payment are annoying but manageable. The real danger is the third instalment arriving two weeks later while the second is still unpaid, and both bouncing. That’s when people reach for a second loan from a different lender, and that’s how one $600 problem becomes two.
What Lenders and Collectors Can’t Do in Alberta
Alberta’s consumer protection rules put clear limits on how a payday lender, and any collection agency it hires, can chase a debt. They can’t:
- Contact you before 7 a.m. or after 10 p.m., Alberta time
- Use threatening, profane or intimidating language, or call so often it amounts to harassment
- Mention police, jail, a lawyer, a lien or garnishment to scare you when that isn’t actually happening
- Discuss your loan with your family, neighbours or co-workers. They may only ask those people how to reach you
- Keep calling you at work after you’ve asked them to stop and given them another way to reach you
- Try to withdraw an instalment before its due date, or take money from your account without your consent
- Pressure a relative or friend to pay a debt they never signed for
Collection agencies also have to be licensed by Service Alberta, use their licensed name, and are limited to three unsolicited contacts in any seven-day period. If anyone breaks these rules, you can file a complaint with Service Alberta.
What to Do Before (or Right After) You Miss a Payment
These steps are listed in the order that usually helps most.
- Call the lender before the due date. This is the single most useful thing you can do. Ask whether the instalment date can move to your next payday, or whether you can pay part of it now. Lenders deal with this every day, and a borrower who calls first usually gets more flexibility than one who goes quiet. Get any new arrangement in writing.
- Pay what you can, when you can. Alberta lets you pay any part of the loan early without penalty. Even $100 toward a $228 instalment reduces the amount that default interest applies to.
- Don’t open a new loan to cover this one. Your lender can’t give you another payday loan while this one is outstanding, but a different lender might. It feels like a fix and usually makes things worse.
- Rework the next two weeks of spending. Look for a bill you can pay a few days late without penalty, a payment plan with a utility, or an employer pay advance. Our list of payday loan alternatives covers the options that tend to work fastest.
- Get free advice if it’s more than one loan. If you owe more than one lender, or you’ve rolled from one loan into another, talk to a non-profit credit counsellor before it goes to collections.
You may be able to cancel the pre-authorized debit with your lender, but that doesn’t cancel what you owe, and it can make the lender less willing to work with you. Talk to the lender first.
Free Help in Edmonton and Across Alberta
If the problem is bigger than one instalment, you don’t have to sort it out alone, and you shouldn’t pay a company to do it for you.
- Money Mentors is Alberta’s non-profit credit counselling service, with offices in Edmonton and Calgary and free phone and online appointments. A counsellor can look at your whole budget and, if it makes sense, set up a debt repayment program with your creditors.
- 211 Alberta (dial 2-1-1) connects you to local help such as rent assistance, food banks and emergency benefits, which can free up the cash you need for the loan.
- A Licensed Insolvency Trustee can explain a consumer proposal if payday loans are only part of a larger debt problem. Your first consultation is free.
- Service Alberta handles complaints about payday lenders and collection agencies that break the rules.
Be careful with debt relief companies that charge upfront fees or promise to make your debt disappear. In Alberta, debt repayment agencies have to be licensed and must give you a written contract listing every fee.
Borrowing Again After a Rough Patch
Once the loan is paid off, it’s worth taking stock before you borrow again. Ask yourself whether the gap was a one-off, like a car repair, or something that comes back every month. A payday loan can bridge a one-off gap. It can’t fix a monthly shortfall, and it gets expensive fast when it’s used that way.
If you do need a short-term loan again, borrow only what one instalment schedule can comfortably absorb. Choose instalment dates that land right after your paydays, and keep the agreement where you’ll see it. If you live in the capital region, our page on payday loans in Edmonton explains how e-Transfer funding and local rules work there. Borrowers elsewhere can start with our Calgary and Red Deer guides, or the province-wide Alberta payday loan rules.
Frequently Asked Questions
Can I go to jail for not paying a payday loan in Alberta?
No. An unpaid payday loan is a civil debt, not a crime. Police don’t collect debts, and a lender or collector who threatens you with arrest is breaking Alberta’s collection rules.
Can a payday lender garnish my wages in Alberta?
Only after it sues you and wins a court judgment. Missing a payment doesn’t give a lender the right to take your wages. It has to go to court first.
How much extra does a missed payment cost in Alberta?
The lender can charge a one-time dishonoured payment fee, capped by regulation, plus interest of up to 2.5% a month on the overdue amount. Your bank may charge its own NSF fee as well. These charges are on top of the original borrowing cost.
Can my lender give me a new loan to pay off the old one?
No. Alberta lenders can’t give you a new payday loan while you still owe on an existing one. Taking a loan from a different lender to cover the first is legal, but it usually deepens the problem.
Will a missed payday loan payment hurt my credit?
Usually not right away, because many payday lenders don’t report to the credit bureaus. If the debt goes to a collection agency, though, a collection account can appear on your credit report and stay there for several years.
Who can help me if I owe more than one payday lender?
Start with a non-profit credit counsellor such as Money Mentors, which serves Edmonton, Calgary and the rest of Alberta at no cost. They can review your budget and talk to your lenders on your behalf.
This article is general information, not legal or financial advice. Reviewed against Alberta’s Consumer Protection Act, Service Alberta guidance on collection practices, and the federal payday loan cost limit in November 2026. Check your own loan agreement for the exact fees that apply to you.