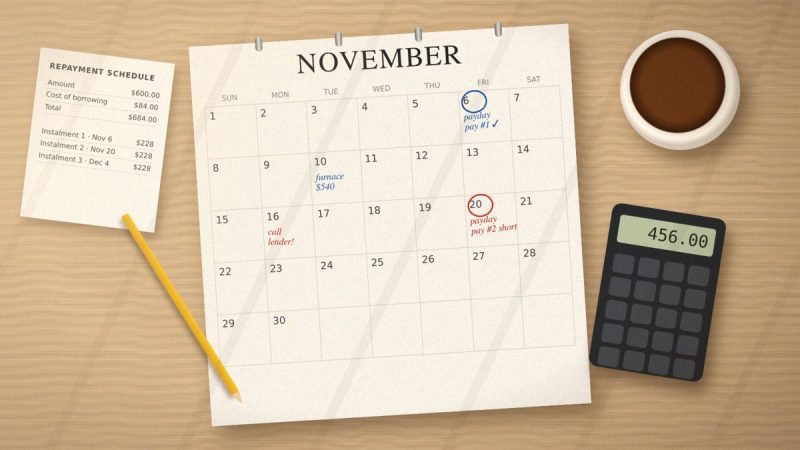
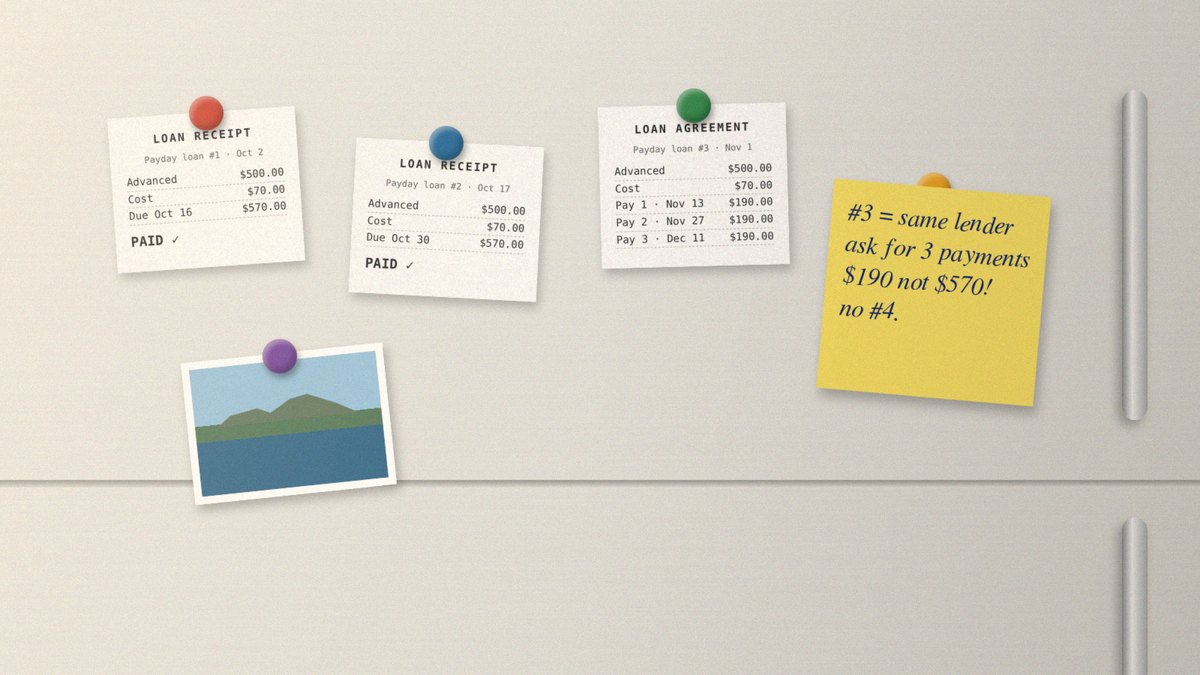
Most people don’t plan to take a second payday loan. The first one covers a short month. Then repaying it leaves the next paycheque short, so a second loan covers that. By the time a third one looks necessary, the loan is no longer covering an emergency. It’s covering the last loan.
This happens a lot. Consumer Protection BC, which licenses payday lenders in the province, has reported that BC borrowers take out about four to five payday loans a year on average. BC’s law has a specific rule for this situation, and it’s one of the most useful and least known protections in the province. This guide explains how it works, where it falls short, and what it looks like for borrowers in Vancouver and Kelowna.
What BC Law Says About Borrowing Again
Three rules apply when you go back to a payday lender in BC:
- One loan at a time. A lender can’t give you a new payday loan while you still owe on one from them.
- No paid rollovers. A lender can’t roll an unpaid loan into a new one with fresh charges. You have to repay the first loan before you can borrow again.
- The third-loan rule. If this is your third payday loan from the same lender in two months, the lender must let you repay it over two or three pay periods instead of all at once.
The full list, including the 50% of net pay limit and the two-day cancellation right, is in our guide to British Columbia payday loan rules.
How the Third-Loan Rule Changes the Math
A normal BC payday loan is due in one payment on your next payday. That single payment is what drives the repeat cycle. If you borrow $500, you’ll owe $570 two weeks later, which is a big bite out of one paycheque. The third-loan rule spreads that bite out.
| Repaying a $500 loan ($70 cost) | Single payment | Over 2 pay periods | Over 3 pay periods |
|---|---|---|---|
| Each payment | $570 | $285 | $190 |
| Paycheques it touches | 1 | 2 | 3 |
| Extra cost for spreading it out | – | $0 | $0 |
The cost doesn’t go up. You pay the same $70 either way. What changes is how much of any one paycheque goes to the lender. For someone stuck in a cycle, that’s often the difference between breaking even and needing a fourth loan.
The Gap Most Borrowers Miss: It’s Counted Per Lender
The rule applies to your third loan from the same lender. Switching to a different lender for loan number three generally resets the count. You get a standard single-payment loan again, and the protection is gone.
That’s why moving between lenders is risky. It’s easy to do online, and it can feel like a fresh start, but it often means giving up the one rule built to help repeat borrowers. If you’re already on your second loan with one lender and you know you’ll need a third, it’s usually better to stay with that lender and ask about the instalment option.
You don’t have to wait for loan number three either. Some lenders will agree to a payment plan earlier if you ask. They aren’t required to, but asking costs nothing. You can also repay any amount early with no penalty, so a partial payment from one paycheque reduces what’s due on the next.
What It Looks Like in Vancouver
Take a renter in East Vancouver who takes home $2,100 every two weeks. Rent comes out of the first paycheque of the month, and most months that’s fine. Then a dental bill and a BC Hydro bill land in the same week. She borrows $500, repays $570 on payday, comes up short again, and borrows another $500 two weeks later.
When she needs a third loan from the same lender, the rule applies. Instead of $570 coming out of one paycheque, the lender has to offer three payments of $190 or two of $285. With $190 a payday and rent still due, she can get through the following month without borrowing again. With a fourth single-payment loan, she probably couldn’t.
For renters in Metro Vancouver, the bigger lesson is to deal with rent separately. The Vancouver Rent Bank, part of the BC Rent Bank network, offers interest-free, repayable loans to eligible renters who can’t cover rent because of a short-term crisis. That costs far less than a payday loan. Our page on payday loans in Vancouver lists other local options and explains how licensed online lenders work in the city.
What It Looks Like in Kelowna
Kelowna’s problem is usually timing rather than income. Imagine a server at a lakeside restaurant whose take-home pay drops from about $1,500 to $900 every two weeks once the tourists leave in the fall. The 50% rule caps a single-payday loan at $450 on that lower income. That’s the right limit, but it means the same cash gap needs more loans to cover it.
Two loans in October and a third in November would trigger the rule, spreading the third repayment across the slow pay periods until hours pick up again. It’s still borrowing against a thinner paycheque, so the safer plan is to borrow less and lean on cheaper help first. The Central Okanagan Rent Bank, run by the Canadian Mental Health Association in Kelowna, offers interest-free rent loans to eligible renters in Kelowna, West Kelowna, Lake Country and Peachland. Our page on payday loans in Kelowna covers seasonal income in more detail.
Signs the Loans Are Covering Each Other
It’s easy to miss the moment a short-term fix becomes a cycle. These are the signs to watch for:
- You’re borrowing roughly the same amount on roughly the same date each month
- Most of a new loan goes to replacing the money that paid off the last one
- You’ve switched lenders because your usual one turned you down or made you wait
- You know the exact repayment amount without checking
- You’ve stopped thinking of it as a loan and started thinking of it as part of your pay
If two or more of these sound familiar, more payday loans won’t fix the problem. You need to change how the money flows for a month or two.
Ways Out of the Cycle in BC
- Ask for the instalment option, and get it in writing. On a third loan from the same lender, it’s your right. Before that, ask anyway.
- Pay down early whenever you can. Any amount, any time, with no penalty. Small payments now shrink the lump due later.
- Look at a credit union small-dollar loan. Vancity’s Fair & Fast Loan, for example, lets BC residents borrow a few hundred to a couple of thousand dollars at a credit union rate and repay it over months, with approval based on income. Check current terms and membership requirements with Vancity.
- Use a rent bank for rent. If housing costs are what keep you short, a local rent bank loan is interest-free.
- Talk to a non-profit credit counsellor. The Credit Counselling Society is a BC-based non-profit that offers free advice and can help you build a plan if you owe several lenders.
Our list of payday loan alternatives in Canada covers more options, including employer pay advances and utility payment plans.
What a BC Lender Can’t Do When You Come Back
Repeat borrowers sometimes get treated like regulars, and a few practices are off limits no matter how many loans you’ve taken:
- Lend you more than 50% of your net pay for the loan term
- Charge more than $14 per $100 borrowed, all fees included
- Require or even ask you to buy insurance on the loan
- Roll your loan over or extend it for a fee
- Charge more than 30% a year on a late amount, plus one $20 returned-payment fee
If a lender breaks these rules, you can contact Consumer Protection BC, which can investigate and fine licensed lenders.
Frequently Asked Questions
What is the third payday loan rule in BC?
If you take a third payday loan from the same lender within two months, the lender must let you repay it over two or three pay periods instead of in one lump sum. The cost of the loan stays the same.
Can I have two payday loans at once in BC?
Not from the same lender. A BC payday lender can’t give you a new loan while you still owe on an existing one. Another lender may be able to, but borrowing from two lenders at once raises the risk that you won’t be able to repay either.
Does the third-loan rule apply if I switch lenders?
Generally no. The rule counts loans from the same lender, so a third loan from a new lender is usually a standard single-payment loan.
Does spreading out the payments cost more?
No. The borrowing cost is capped at $14 per $100 borrowed whether you repay in one payment or over two or three pay periods.
Can I pay off a BC payday loan early?
Yes. You can repay all or part of a payday loan at any time before it’s due, with no penalty or extra charge.
Where can renters in Vancouver and Kelowna get help with rent instead?
The Vancouver Rent Bank and the Central Okanagan Rent Bank, both part of the BC Rent Bank network, offer interest-free, repayable loans to eligible renters facing a short-term shortfall.
This article is general information, not legal or financial advice. Reviewed against the Government of BC’s payday loan guidance, Consumer Protection BC’s payday lending backgrounder and the federal payday loan cost limit in November 2026. Credit union and rent bank programs change, so confirm current terms directly with them.